
A handover date can be approaching while mortgage paperwork is still moving between the lender and developer. For off-plan buyers, mortgage coordination services Dubai can connect financing follow-up with property milestones, so each step is easier to track.
The process can feel fragmented. Lender requirements, developer paperwork, valuation reports and transfer documents may all need attention at different stages. Mortgage coordination does not replace mortgage advice or secure loan approval. It connects clients with mortgage advisers, tracks financing progress and supports valuation and conveyancing administration alongside the transaction.
This guide explains what a coordinator handles, where the adviser’s role begins and ends, and how financing steps can be tracked against the SPA payment schedule and handover process. It also covers what information to organize and how to keep lender, developer and transfer follow-up in sequence. ASMA Property Services provides mortgage coordination as part of its wider Dubai property transaction work, including lender and developer coordination and assistance with valuation reports.
Key Takeaways
- Map financing follow-up against the SPA payment schedule and handover milestones, using the SPA as the reference for your obligations.
- Use mortgage coordination services Dubai to track financing steps and connect with mortgage advisers, without confusing coordination with lending or loan approval.
- Separate the responsibilities of the mortgage adviser, lender, conveyancer, developer and coordinator so each task goes to the right party.
- Organize available property, financing, identity and transaction information before a case review. Lender requirements may vary.
- Adviser connections, financing-step tracking and valuation-report assistance can sit alongside conveyancing administration.
Why mortgage coordination matters at an off-plan property handover in Dubai
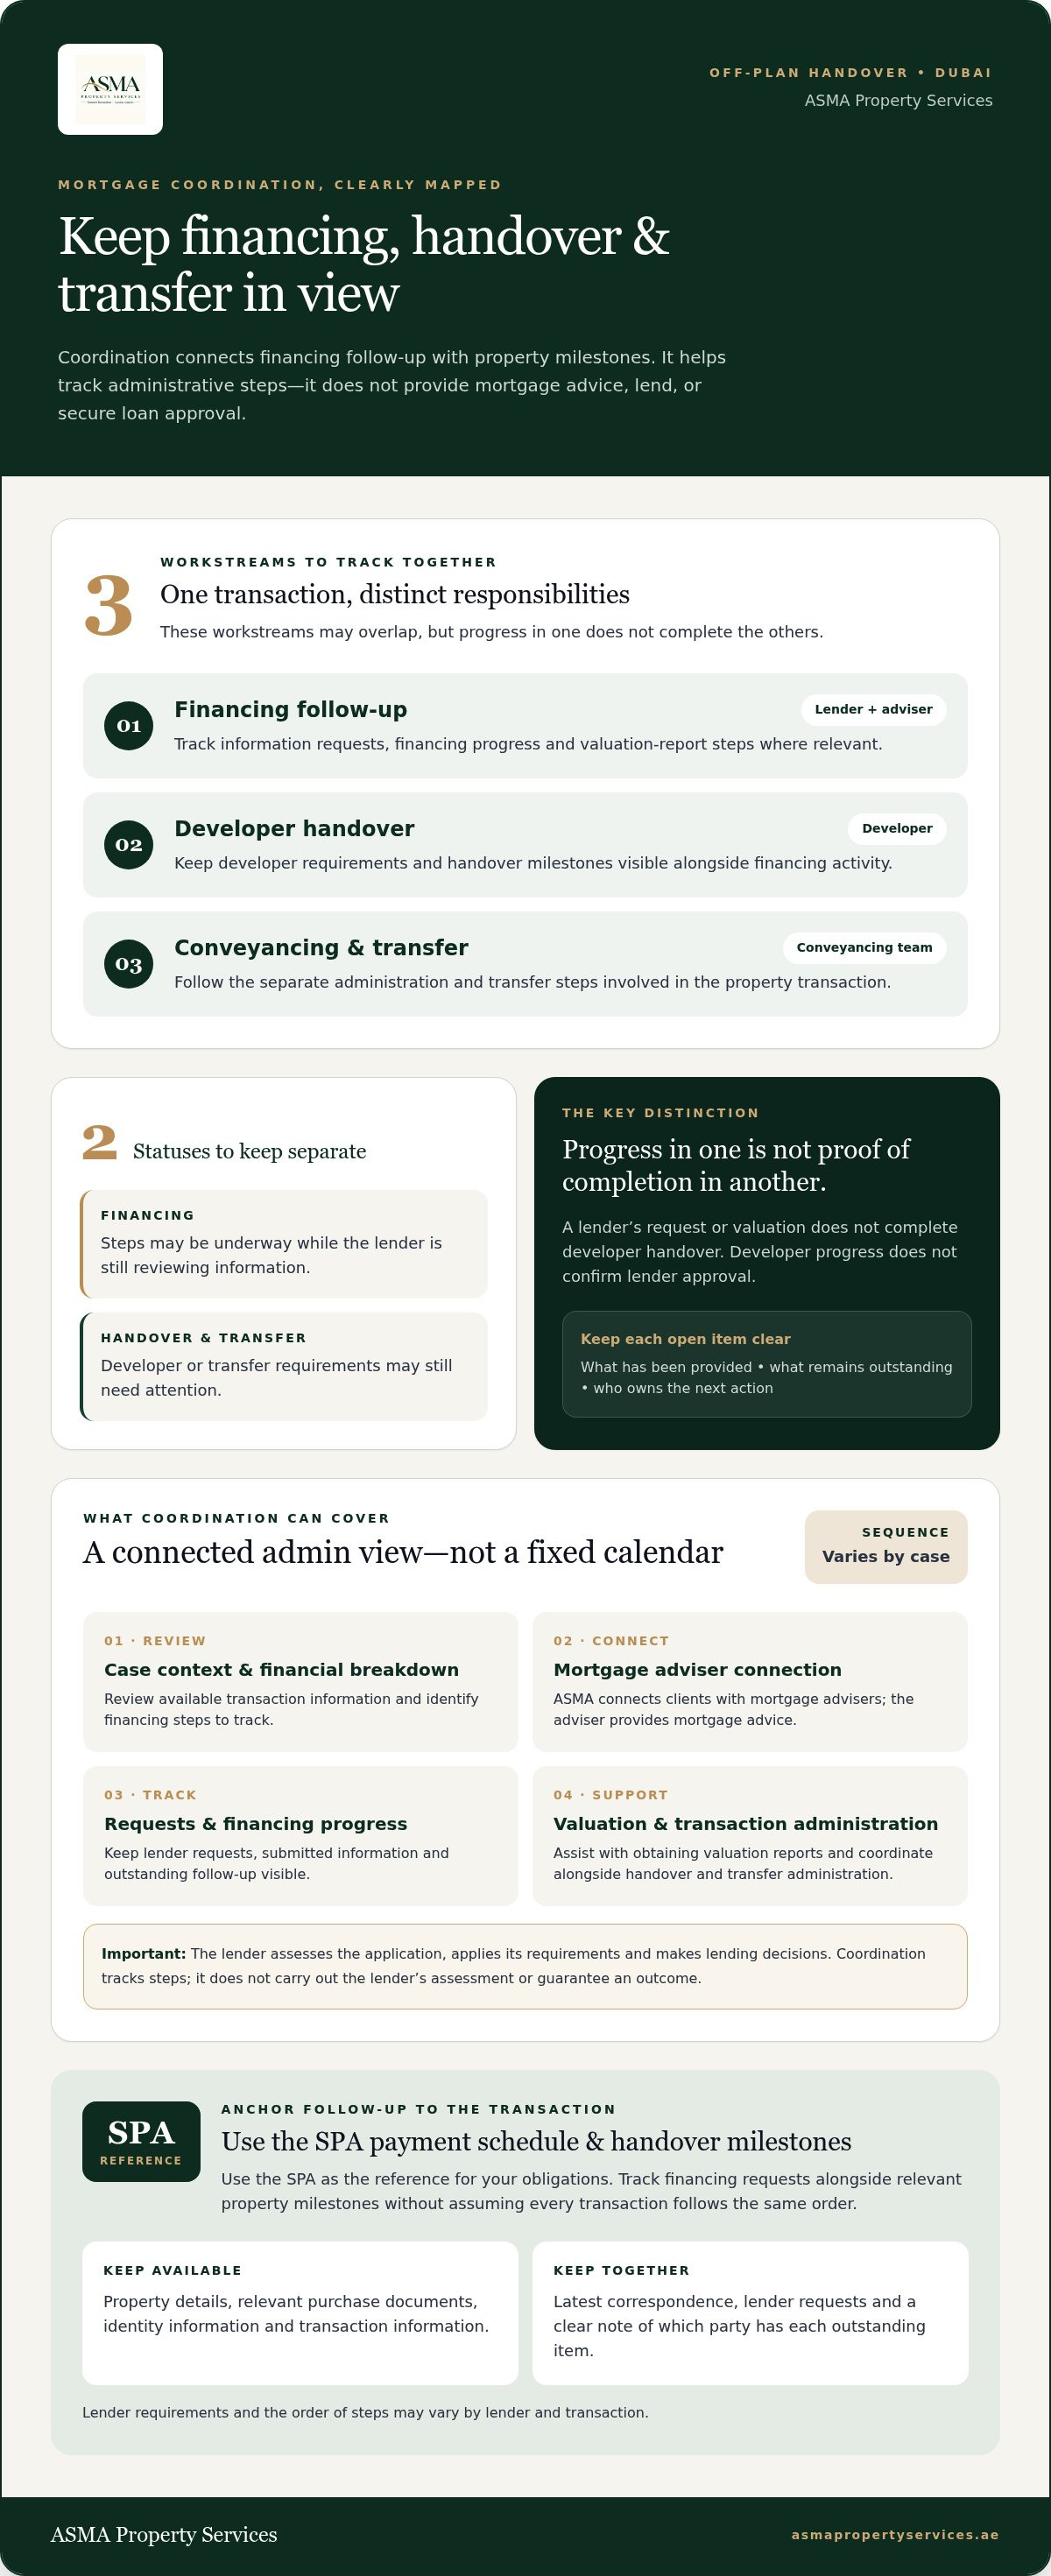
An off-plan handover brings several workstreams together. The developer may communicate payment and handover requirements, the lender may request financing information or a valuation, and conveyancing administration may involve its own documents and transfer steps. Each workstream serves a different purpose. If an update or document is outstanding in one, the buyer may be unsure what remains to be done, even when other preparations are progressing.
Mortgage coordination for a Dubai property handover means organizing financing steps and related communication alongside property milestones. It is not a loan, mortgage advice or approval. A mortgage loan is financing arranged through a lender. Coordination helps keep the related administrative steps visible as the transaction moves toward handover.
Where financing steps meet the off-plan handover
Buyers need to monitor financing progress while preparing for the developer’s handover requirements. These workstreams may overlap, but they are not interchangeable. A lender’s request for information or a valuation report does not complete the developer’s handover process. Similarly, progress with the developer does not mean the lender has completed its review.
Communication may involve the buyer, lender, developer and conveyancing team. Tracking who needs what, what has been provided and what follow-up remains makes the status easier to understand. Requirements and their order vary by lender and transaction, so there is no single sequence for every off-plan purchase.
For example, a buyer may be preparing for a developer milestone while the lender is still reviewing financing information. Keeping both workstreams in view helps identify the next action without treating either as complete prematurely. Mortgage coordination services Dubai can provide an administrative link between financing follow-up and transaction milestones.
What a mortgage coordinator does, and does not do
A coordinator organizes communication and tracks progress. ASMA connects clients with mortgage advisers, follows financing steps and assists with obtaining valuation reports. These tasks can sit alongside wider conveyancing administration, keeping transaction information connected rather than scattered across separate follow-ups.
The responsibilities remain distinct. A mortgage adviser provides mortgage advice. The lender assesses the application, applies its requirements and makes lending decisions, including approval. A coordinator does not lend, provide loan approval or carry out the lender’s assessment. Coordination supports the process but does not determine its outcome.
Financing readiness and handover completion are separate statuses. A buyer may have financing steps underway while still needing to meet developer or transfer requirements. Progress toward handover does not confirm that a lender has approved financing. Keep each milestone visible, record who owns each outstanding action, and do not treat one party’s progress as confirmation from another.
How mortgage coordination works through Dubai handover milestones
Mortgage coordination follows the transaction’s requirements rather than a fixed calendar. The work can include case review, a financial breakdown, an adviser connection, financing-step tracking, valuation-report assistance where relevant, and coordination with parties involved in handover and transfer administration. The sequence varies by property, lender and outstanding requirements.
For an off-plan buyer, the practical value is a clearer record of open items. Financing requests can be tracked alongside related property milestones, with follow-up directed to the relevant party. Coordination does not set lender deadlines or guarantee a decision. It helps distinguish what has been submitted, what remains outstanding and who is responsible for the next action.
From case review to financing follow-up
The process starts with understanding the transaction. Case analysis and a financial breakdown help establish the property context and identify financing steps to track. The review can draw on available transaction information, such as property details and relevant purchase documents.
ASMA connects clients with mortgage advisers and tracks financing progress. If the lender or adviser requests information, coordination can keep the request and its status visible. The documents involved depend on the transaction and lender, so there is no universal checklist. Buyers can support clear follow-up by keeping the latest correspondence together and noting which party has each outstanding item.
Mortgage coordination services Dubai can link financial follow-up with property administration without taking over the lender’s assessment. A request for more information remains a lender matter. The coordinator tracks the step and its place in the wider transaction.
Valuation and transfer administration near handover
A valuation report may form part of financing requirements. ASMA assists with obtaining valuation reports and can track this step alongside other financing follow-up. The report does not guarantee a lending decision. The lender determines how it is assessed within its process.
As handover preparations progress, communication may involve the developer, lender and conveyancing team. Where relevant, coordination can also involve trustee offices and the Dubai Land Department (DLD). These parties handle different parts of the process. Keeping communications and open actions organized helps prevent a financing task from being mistaken for a completed transfer requirement, or the reverse.
Transfer administration has its own documents and milestones. For more context, the Dubai property conveyancing guide explains how transfers are coordinated in Dubai. Buyers preparing an off-plan case can use ASMA’s mortgage coordination support to organize financing follow-up alongside wider transaction administration.
Mortgage adviser, lender, conveyancer, or coordinator: who handles what?
Off-plan handover involves several parties, but their responsibilities are different. A buyer may receive a financing request while also managing developer communications and transfer administration. Knowing who owns each task helps direct questions and documents correctly. The coordinator connects the workstreams; the adviser, lender, developer and conveyancer retain their distinct roles.
| Party | Primary role | What this means for the buyer |
|---|---|---|
| Mortgage adviser | Discusses financing and provides mortgage advice. | Direct financing questions and advice needs to the adviser. |
| Lender | Reviews the application, conducts its assessment and makes lending decisions. | Provide requested information through the lender’s process. Only the lender determines its decision. |
| Conveyancer | Supports property transaction administration, including conveyancing and relevant contract preparation or review. | Coordinate transaction documents and transfer-related steps with the parties involved. |
| Developer | Communicates project-specific payment and handover requirements. | Track developer requirements separately from lender requests. |
| Coordinator | Organizes communication and tracks financing steps alongside transaction milestones. | Keep track of outstanding actions and the party responsible for each follow-up. |
Mortgage adviser and lender responsibilities
The adviser provides advice; the lender assesses the application and makes lending decisions. These functions remain separate while the buyer works toward handover. ASMA connects clients with mortgage advisers and tracks financing steps, but does not provide mortgage advice, make lending decisions or determine approval outcomes.
This distinction gives each query a clear destination. Questions about financing advice belong with the adviser; application assessment and lending decisions belong with the lender. Coordination keeps related follow-up visible without substituting for either party’s specialist work.
Conveyancing and coordination responsibilities
Conveyancing support concerns the property transaction and its administration. ASMA’s wider work includes case analysis, contract preparation and review, and coordination with lenders, developers, trustee offices and the Dubai Land Department where relevant. The coordinator connects financing administration with transfer-related communication, so an open lender item is not confused with an outstanding property document.
Communication can overlap, but authority does not. A coordinator can record a request and track its progress; the lender still decides financing matters. Contract review supports transaction administration; it does not replace specialist legal advice. Valuation reports may be coordinated, but assessment of the findings for lending remains with the relevant valuation professional and lender.
Requirements vary by lender, property and individual case. Treat the table as a guide to roles, not a universal checklist. For mortgage coordination services Dubai, the practical benefit is a clearer division of responsibility: advice goes to the adviser, decisions to the lender, property requirements to the developer, transfer administration to conveyancing, and follow-up tracking to the coordinator.
What to prepare before arranging off-plan handover mortgage coordination
A focused case review starts with organized information, not a universal document pack. Gather what you have about the property, financing, identity and transaction. Requirements differ by lender, property and case, and relevant authorities may set their own requirements. Preparation helps make the transaction easier to review and shows which financing or handover actions remain open.
Property and financing information to organize
Keep available records together in one accessible digital or physical folder. Include property and purchase details, relevant developer communications, and correspondence with a lender or mortgage adviser. If you have received a request for information, retain the request and note whether you have responded.
- Property: Record the unit or property details and the purchase information available to you.
- Developer: Keep payment, handover and other transaction communications together, including updates that affect your next milestone.
- Financing: Organize adviser and lender correspondence, financing progress notes and outstanding requests.
- Identity and transaction: Keep relevant identity and purchase information available for case review, without assuming every item is required by every party.
- Valuation: Note whether a valuation report has been requested, obtained or remains outstanding.
This is a preparation aid, not a lender document checklist. Do not assume a document is mandatory because it appeared in another buyer’s process. The lender, transaction and relevant authorities determine what information applies to the specific case.
Questions to resolve before the next milestone
Before a handover or financing milestone, write down the open actions and who owns them. A simple record can prevent repeated follow-up or the assumption that another party has already responded.
- Which financing requests are still outstanding, and who is expected to respond?
- Does the case involve a mortgage adviser connection or further adviser discussion?
- Is a valuation report relevant to the current financing steps, and what is its status?
- Which developer or transfer-related action is approaching, and what information is needed?
- Has an update from the lender, developer or conveyancing team changed the next action?
Update the list as messages arrive. A status such as “sent,” “awaiting response” or “completed” is more useful than an untracked email thread. Mortgage coordination services Dubai can organize financing follow-up within the wider property transaction, while lender-specific requirements and decisions remain with the lender.
With the property records and open actions organized, arrange mortgage coordination with ASMA to connect financing follow-up with transaction milestones.
ASMA mortgage coordination services in Dubai: scope and next steps
ASMA’s mortgage coordination connects financing follow-up with the wider property transaction. The service connects clients with mortgage advisers, tracks financing steps and assists with obtaining valuation reports. It does not provide lending, mortgage advice or loan approval. The lender remains responsible for assessing an application and making lending decisions.
For off-plan buyers, this work can sit alongside conveyancing administration and transaction milestone support. Case analysis, contract preparation and review, and communication with relevant parties help keep property tasks visible alongside financing actions. The goal is administrative clarity: know what is outstanding, who is handling it and how it relates to the transaction. Coordination does not guarantee a financing outcome or handover completion.
A structured coordination process
ASMA uses a milestone-driven process with clear communication. Work is organized around the instruction and transaction, rather than a fixed sequence that assumes every lender or property follows the same path. Financing follow-up can be tracked alongside developer communications, valuation-report assistance and transfer administration.
Where relevant, transaction coordination may involve lenders, developers, trustee offices and the Dubai Land Department. Each party retains its own responsibilities. ASMA organizes communication and tracks steps within its coordination scope; it does not make lender decisions or replace the functions of the relevant authority. Service scope, fees and timelines are confirmed for each instruction, giving the buyer a defined basis for proceeding.
This structure keeps separate workstreams clear. For example, an outstanding financing request can be recorded alongside a developer or transfer milestone without treating one as proof that the other is complete. Clear status tracking supports follow-up; it does not set another party’s decision or completion date.
Experience and client next steps
ASMA Property Services has operated since 2022 and has completed more than 3,000 successful property transfers. Co-founder Suhail Ibrahim has handled over 3,000 property transactions. Co-founder Mariam Gani Ibrahim has served over 1,000 satisfied customers. These figures describe experience, not a promise of a particular lending decision, timeline or handover outcome.
To begin, bring together the property and purchase details available to you, developer communications, financing correspondence and any open requests. This gives the case review a practical starting point. The next step is to identify which financing actions need tracking, whether an adviser connection or valuation-report assistance is relevant, and how those actions relate to property milestones.
For mortgage coordination services Dubai buyers can use alongside conveyancing administration, discuss mortgage coordination for a Dubai property with ASMA. The discussion can establish the instruction’s scope and the information needed to organize next steps.
Set the next handover steps in motion
Before the next property milestone, make open actions visible. Keep the latest lender and developer updates together, note what is pending and identify who is responsible for each follow-up. This creates a practical starting point and helps prevent new requests from getting lost in separate email threads.
Mortgage coordination services Dubai buyers use can bring financing follow-up into the wider property workflow while leaving lending decisions with the lender. The next step is to clarify the coordination scope for your transaction and the information needed to begin. Clear expectations make it easier to organize the work.
ASMA Property Services provides milestone-driven coordination with clear communication. Discuss mortgage coordination for your Dubai property and outline the handover stage, financing progress and outstanding tasks. A clear starting record makes the next actions easier to organize and keeps the process focused.
Frequently Asked Questions
What are mortgage coordination services in Dubai?
Mortgage coordination services Dubai buyers use are administrative support for organizing financing steps during a purchase or handover. A coordinator can connect clients with mortgage advisers, track progress and assist with obtaining valuation reports where relevant. This differs from mortgage advice, lending and approval, which belong to the adviser or lender. The coordination scope depends on the property transaction and the instruction, including which financing tasks need follow-up.
Can a mortgage coordinator help with an off-plan property handover in Dubai?
Yes. Coordination can track financing actions alongside property milestones, connect the buyer with mortgage advisers and assist with valuation reports where relevant. For example, if a lender requests information while the developer is communicating about handover, tracking each open action can clarify who needs to respond. Requirements vary by lender and case. A coordinator does not approve finance, control the developer’s handover process or promise an outcome or completion date.
What is the difference between a mortgage adviser and a mortgage coordinator?
A mortgage adviser supports discussions about financing; a coordinator organizes communication and tracks related administrative steps. The lender assesses the application and makes lending decisions. ASMA’s coordination includes connecting clients with advisers, tracking financing steps and assisting with valuation reports. For example, a buyer seeking financing advice speaks with an adviser, while coordination tracks outstanding requests and their status. ASMA does not provide lending or mortgage advice.
Does mortgage coordination guarantee mortgage approval in Dubai?
No. Mortgage coordination does not guarantee approval. The lender reviews the application and makes its decision through its own process. A coordinator can organize communication and track financing actions, but cannot control the lender’s assessment. A valuation report, conveyancing support or progress toward property handover does not change who decides whether to lend. Treat coordination as administrative support, not confirmation that financing has been or will be approved.
What information should I prepare for mortgage coordination on an off-plan property?
Gather the property and purchase details you have, developer communications, financing correspondence and any lender requests already received. For example, keep the latest request for information with a note of whether you have replied. This is preparation guidance, not a universal list of required documents. The lender, property and transaction determine specific requirements, so do not treat an item as mandatory unless the relevant party has requested it for your case.
How much do mortgage coordination services in Dubai cost?
Fees are confirmed for each instruction, and the scope depends on the coordination requested and the property transaction. An instruction involving adviser connection, financing-step tracking or valuation-report assistance may have different requirements from another case. Confirm the agreed scope and applicable fees for your instruction before proceeding; do not assume a standard market fee or savings.
How long does mortgage coordination take for an off-plan handover?
No fixed duration applies to every case. The time involved depends on the transaction, lender requirements, outstanding information and the processes of relevant parties, including the developer. ASMA confirms its service scope and timelines for each instruction. Coordination is separate from lender approval and the developer’s handover date, neither of which the coordinator controls. Tracking open actions can clarify progress, but it cannot set another party’s decision or schedule.
Article by
Suhail Ibrahim
Suhail has guided more than 3,000 Dubai property transactions and built the reputation that leading brokerages rely on — calm under pressure, precise with paperwork, and always reachable when a deal needs completing.


